
Ellington eyes non-QM servicing growth in new acquisition
Ellington Financial believes its new servicer acquisition presents it with opportunity to stand out in the specialized, growing segments it operates in and holds potential to attract future customers also active in the space.
Processing Content
The real estate investment trust announced its purchase this week of Statebridge Co., a diversified loan servicer, whose expertise primarily covers late-stage distress, along with residential-transition and other non-qualified mortgages.
The move points to the diversification strategy occurring across mortgage businesses of all types, in response to changing expectations in origination mix and borrower performance over the coming months.
The decision to acquire a servicer came about, in part, from industry contraction, which made it challenging for Ellington to find a partner that could effectively work with the types of delinquent and non-QM loans it owns. The company hinted at the likely merger over the summer in its second-quarter earnings.
“We didn’t see great options where we could really get what we think are best-in-class protocols, and have a dialog and be able to use our data analysis and our kind of native experience and expertise in the product to effectuate outcomes,” said Ellington Co-Chief Investment Officer Mark Tecotzky on Thursday in its latest earnings call.
While leaders advised that financial benefits might not appear on the balance sheet immediately, the upside would come in the longer term.
“We’re going to build this into the premier special servicer,” added CEO Larry Penn. “Even with what we see as the delinquency pipeline now, once we’ve built this, I think there’ll be plenty of business for Statebridge to grow and thrive on.”
As of September 30, Statebridge serviced approximately 14,700 loans representing an approximate unpaid principal balance of $1.9 billion, nearly all for third-party clients. The portfolio includes 3,500 non-QM and RTL loans, with balances totaling $1.1 billion, as well as a smaller subset of agency and commercial mortgages.
With the attention now paid to the non-QM segment, the need to understand the nuances of those particular types of loans will also give Statebridge an advantage, Tecotzky explained.
“Delinquencies when non-QM first started were trivially small,” he said, noting the effect of Covid-era home-price appreciation on the housing market. “We don’t see that HPA tailwind right now obviously, so we think long-term delinquencies will tick up to levels that are more consistent with reasonable expectations.”
“As we build this out, and we demonstrate the quality of the resolutions we believe Statebridge can get, others may want to use their services,” Tecotzky continued.
Ellington and Longbridge post “solid” third quarter
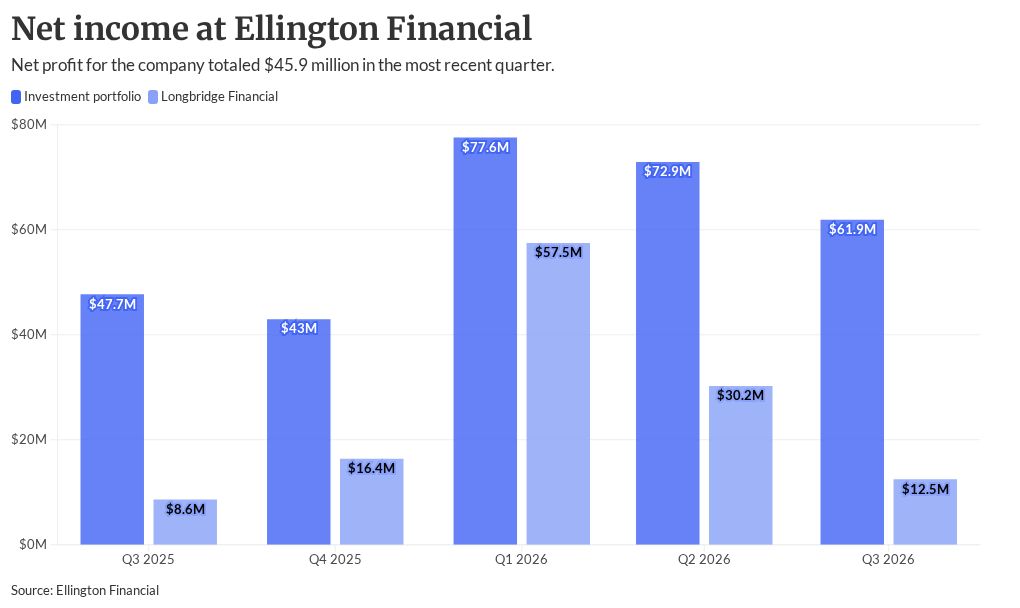
The acquisition came in a third quarter when Ellington reported net income of $45.9 million, which represented a 20.9% decrease from the prior three-month period’s $58 million. On a year-over-year basis, profit climbed 21.6% from $37.8 million. The bottom line numbers factored in results across its businesses, including its investment portfolio and reverse lending unit, Longbridge Financial, as well as changes in fair market value.
“This was a solid quarter for EFC, against a market backdrop that has a lot more landmines than in the first half of the year,” Tecotzky said. The portfolio investment arm was able to price two non-QM securitizations and a single agency-eligible transaction early in the quarter before spreads widened, he noted.
With increased interest in non-QM and non-agency loans, the pace of such deals is approaching $5 billion a week, Ellington officials also noted. Interest rate pressures, though, led the company to introduce a sequential pay structure to address investor concerns about reduced refinance incentive.
“Other non-QM issuers quickly adopted that approach,” Tecotzky said.
Net income at the Longbridge subsidiary came in at $12.5 million, 58.8% below the second-quarter’s $30.2 million. Compared to a year ago, the reverse-lending business increased its profit by 4.5% from $8.6 million.
Longbridge celebrated originations of $676.3 million during the third quarter, with volume rising 36% from the same three months in 2025. From July to September, the company grew its share of government-backed Home Equity Conversion Mortgage transactions to a record 31%, making it the second-largest issuer in the market.
Meanwhile, among its proprietary offerings, September proved to be the strongest month ever for the products.
“If anything, we’re hoping for and expecting continued growth into next year,” Penn said. “We do see the product continues to gain traction. Demographics are favorable, and I think the product makes a lot of sense. Obviously, we’re broadening the product base as well.”
Source: www.nationalmortgagenews.com — article syndicated from the publisher’s feed; all rights remain with the original publisher.